
So is teer winning taxable? The short answer is yes. Every rupee you win from a teer draw, whether it comes from the Shillong, Juwai, or Khanapara session, counts as taxable income in India. The prize is taxed at a flat rate of 30 percent under a special provision of the Income-tax Act, and a 4 percent health and education cess is added on top of that tax. No slab benefit applies, no deduction is allowed for the cost of your tickets, and the fact that the winnings arrived from a legal state lottery in Meghalaya does not exempt them. If you play teer, this is one of the most useful facts you can know, because the tax math changes what a win is actually worth in your pocket.

Is Teer Winning Taxable? The Straight Answer
Yes. Indian tax law treats teer prizes exactly the way it treats lottery winnings from any other source. The moment your number matches and the counter pays you, the prize becomes income, and income gets taxed. There is no special exemption for teer, no holiday for small towns, and no distinction between the first round and the second round. A win in the Shillong afternoon session and a win in the Khanapara evening session are taxed by the same rulebook.
Many players first learn this the hard way. They collect a prize, spend it freely, and only discover at filing time that the tax department expects its share. That surprise is avoidable. Once you understand the flat rate and the TDS mechanism described below, you can plan for the tax the same day you celebrate the win, and nothing about the process will catch you off guard.
Where the Rule Comes From: Section 115BB
The Income-tax Act, 1961 contains a dedicated provision for exactly this situation. Section 115BB says that income earned from lotteries, crossword puzzles, races including horse races, card games, and other games of any sort is taxed at a flat rate of 30 percent. Teer is a state-licensed lottery based on archery, so its prizes sit squarely inside this provision. Courts and tax officers do not argue about the label; if the prize came from a game of chance organized as a lottery, 115BB applies.
What else falls under the same section
Teer shares its tax bucket with a long list of winnings. Television game show prizes, horse race winnings, casino jackpots where legal, and prize money from puzzle competitions all face the same flat 30 percent. This matters because it tells you something about the intent of the law. The government decided long ago that windfall income should be taxed at a single clear rate rather than folded into the normal slab system. For background on how India’s tax framework is organized, the Wikipedia page on income tax in India gives a useful overview of the broader system this rule sits inside.
Why teer is treated as a lottery win
Teer is conducted as a legal lottery in Meghalaya, licensed by the state government under the Meghalaya Amusements and Betting Tax Act, and the prize depends on the outcome of archery shooting at grounds like the Polo Ground in Shillong. That makes it a game of chance with a prize pool, which is precisely the shape of income Section 115BB was written to cover. The Khasi Hills archery tradition gives teer its cultural roots, but for tax purposes the roots do not matter; only the prize does.
How the 30 Percent Teer Winning Tax Is Calculated
The calculation is simpler than most players expect, which is good news. Take the gross prize amount, apply 30 percent tax, then add a 4 percent health and education cess on the tax itself. That is the whole formula. There are no slabs to climb through, no rebates to subtract, and no separate treatment for senior citizens on this kind of income.
The three numbers in every teer prize
Think of every winning as splitting into three parts. The first part is the 30 percent income tax on the gross prize. The second part is the 4 percent cess, calculated on the tax amount rather than on the prize. The third part is yours to keep. Put together, the effective burden works out to 31.2 percent of the prize in ordinary cases, since 4 percent of 30 is 1.2. One honest exception exists: at very high income levels a surcharge can be added by law, but for the typical teer prize the three-part split above is the complete picture.
A worked example with a one lakh prize
Say you win Rs 1,00,000 from a single teer round. Thirty percent of that is Rs 30,000 in tax. The 4 percent cess on Rs 30,000 comes to Rs 1,200. Your total tax is therefore Rs 31,200, and the amount that stays with you is Rs 68,800. Notice that the tax was calculated on the full one lakh, not on anything less. Ticket costs, travel to the counter, or a losing ticket from the morning session do not reduce the taxable amount. Once you see this example, you can estimate any prize in seconds: knock off roughly 31 percent and the rest is yours.
TDS on Teer Winnings: What Happens at the Counter
Tax deducted at source, or TDS, is how the government collects part of your teer tax before the money even reaches your hands. When a licensed teer counter in Meghalaya pays out a prize above Rs 10,000, Section 194B of the Income-tax Act requires the payer to deduct 30 percent right there and hand you the balance. You can check the daily numbers for the Shillong, Juwai, and Khanapara sessions on our teer result list, and any prize you collect from those sessions follows the same TDS rule at payout.
The Rs 10,000 threshold explained
The threshold applies to each payment, not to your yearly total. Win Rs 8,000 in the morning round and Rs 9,000 in the evening round, and neither payout crosses the line, so no TDS is deducted on either. Win Rs 25,000 in a single round, and the counter deducts Rs 7,500 before paying you. The threshold decides who deducts tax at payout; it does not decide whether the prize is taxable. Even a Rs 5,000 win is fully taxable income. You simply pay the tax yourself at filing time instead of having it deducted at the counter.
Form 16A and your TDS credit
Whenever TDS is deducted, the payer should issue you a TDS certificate in Form 16A showing the amount paid and the tax deducted. Keep it safe. The deducted amount also appears in your Form 26AS and the Annual Information Statement on the income tax portal, and it counts as advance payment of your final tax bill. Many first-time winners panic when they see the deduction at the counter, but it is not an extra charge. It is the same 30 percent tax being collected early, and you claim credit for every rupee of it when you file.
Is Teer Winning Taxable Even If the Prize Is Small?
It is. This is the single most misunderstood point in teer tax, so it deserves a plain restatement: there is no minimum prize below which the tax disappears. The Rs 10,000 figure you hear about is only the TDS threshold. Below it, the counter pays you in full, but the prize remains taxable income in your hands. You are expected to add it to your total income and pay tax on it when you file your return.
In practice, players with modest wins sometimes wonder whether the department will notice a few thousand rupees. That is the wrong question to ask. The right approach is to keep a simple record of every win, large or small, and report the total honestly. Compliance is cheap when the numbers are small; a clean record costs you nothing and protects you completely.
Deductions You Cannot Claim on Teer Winnings
Normal salary income comes with deductions, exemptions, and rebates. Teer winnings come with none of them. Section 58(4) of the Income-tax Act specifically bars any deduction for expenditure or allowance against income taxed under Section 115BB. That one clause closes several doors at once, and every teer player should know which doors they are.
No deduction for ticket costs
The money you spent buying teer tickets cannot be subtracted from your winnings. If you bought Rs 2,000 worth of tickets over a month and won Rs 50,000 once, the taxable amount is the full Rs 50,000, not Rs 48,000. This feels unfair to many players, but the law is explicit, and arguing the point with an assessing officer will not change it.
No set-off of losses
Section 71(4) adds another wall: losses from lotteries and similar winnings cannot be set off against any other income, and no other loss can be set off against lottery winnings either. Losing tickets from other days, other rounds, or other sessions cannot reduce the tax on the day you win. Each win stands alone for tax purposes, taxed on its gross amount.
No 80C, 80D, or chapter VI-A deductions
The deductions most salaried taxpayers rely on, such as 80C for investments or 80D for insurance premiums, cannot be claimed against 115BB income. The flat 30 percent applies to the gross prize before any of those chapters enter the picture. The rest of your income keeps its normal deductions; only the teer portion is fenced off in this way.
How to Report Teer Prize Income in Your ITR
Reporting is straightforward once you know where the number goes. Teer winnings are declared under the head Income from Other Sources in your income tax return. You show the gross prize, the tax is computed at the flat rate, and you claim credit for any TDS deducted at the counter. File before the due date like any other return, and keep your winning slips and payout receipts with your tax papers for the year.
A few practical habits make this painless. Reconcile the TDS in your Form 26AS with the Form 16A certificates you received, so no credit is missed. If your total income including the prize pushes you into advance tax territory, pay the advance tax in instalments to avoid interest. And if the prize arrived late in the financial year, remember that the income is taxable in the year you received it, not the year the draw happened, which for teer is almost always the same year anyway.
Old regime or new regime: does it matter?
It does not. The choice between the old and new tax regimes changes how your salary and business income are taxed, but Section 115BB income is taxed at the flat rate under either regime. You can pick whichever regime suits the rest of your income without worrying that it alters your teer tax. This is one more way the law keeps windfall income in its own separate lane.
Teer Tax Rules That Every Player Should Memorize
If the sections above felt long, here is the compressed version worth memorizing. Teer prizes are taxed at a flat 30 percent plus 4 percent cess under Section 115BB. No ticket cost, loss, or 80C deduction can touch that income. TDS at 30 percent applies on any single payout above Rs 10,000 under Section 194B, and you claim credit for it in your return. Report the gross prize under Income from Other Sources. That is the entire system in five sentences.
Beyond the numbers, two reminders belong in every teer discussion. Teer is a legal lottery only in Meghalaya, and play is restricted to adults aged 18 and above. Treat it as entertainment with a strict budget, never as a source of income, and never chase a loss by buying more tickets. The tax rules above assume honest play at licensed counters; unlicensed play brings legal risks that no tax planning can fix.
Frequently Asked Questions About Teer Winning Tax
Is a teer prize of Rs 5,000 taxable in India?
Yes. The full Rs 5,000 is taxable income in your hands. No TDS will be deducted at the counter because the payout is below the Rs 10,000 threshold, but you must still add the amount to your total income and pay tax on it when you file your return.
Does the 30 percent tax apply on the net prize after TDS?
The 30 percent applies on the gross prize, and TDS is simply collected out of it in advance. If you won Rs 50,000 and the counter deducted Rs 15,000 as TDS, your taxable prize is still Rs 50,000, and the Rs 15,000 counts toward the tax you owe. You do not pay tax twice.
Can I subtract the cost of losing tickets from my winnings?
No. Section 58(4) of the Income-tax Act disallows any deduction for expenditure against income taxed under Section 115BB. Your taxable prize is the gross amount the counter paid you, regardless of how much you spent on tickets that day, that month, or that year.
Is teer winning taxable if I am a student with no other income?
Yes. The flat 30 percent under Section 115BB applies even if the prize is your only income for the year and even if it sits below the basic exemption limit that normally shields small incomes. Windfall income does not get the benefit of the exemption threshold.
Do I need to file a return if TDS was already deducted on my teer win?
You should. Filing lets you claim credit for the TDS, report the income correctly, and keep your tax record clean. If the TDS deducted matches your actual liability, the return simply confirms that; if too much was deducted, the return is how you claim the refund.
Does the old versus new tax regime change teer tax?
No. Winnings taxed under Section 115BB face the same flat 30 percent plus cess under both regimes. Choose the regime that benefits your salary or business income; your teer winnings are unaffected by the choice.
Where can I check official teer results before claiming a prize?
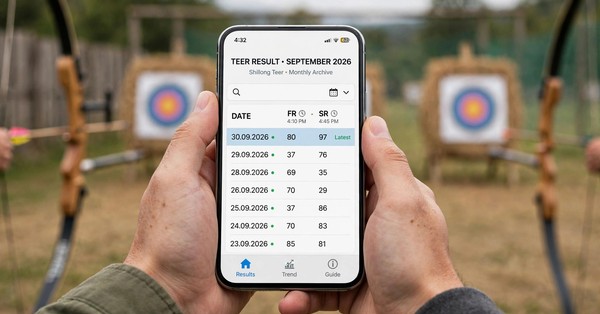
Always confirm your win against an official declaration before collecting. Our Shillong teer result page tracks the daily Shillong sessions, and the Juwai teer result and Khanapara teer result pages cover the other two markets. Start from the homepage for the full daily schedule.
Closing Note
The tax on teer winnings is not a trap; it is a rule, and rules are manageable once they are visible. Thirty percent plus cess, TDS above ten thousand, no deductions, reported under other sources. Keep that chain in mind, keep your slips and Form 16A certificates in one folder, and the tax side of a teer win becomes a small administrative task instead of a year-end surprise. Play responsibly, stay within your budget, and let the numbers be what they are.